
Mortgage credit availability improved in October 2026, but that does not establish your borrower eligibility. The useful next question is whether a lender added a product that fits your situation. Our comparison separates the headline index, its nested segments and the evidence a borrower still needs.
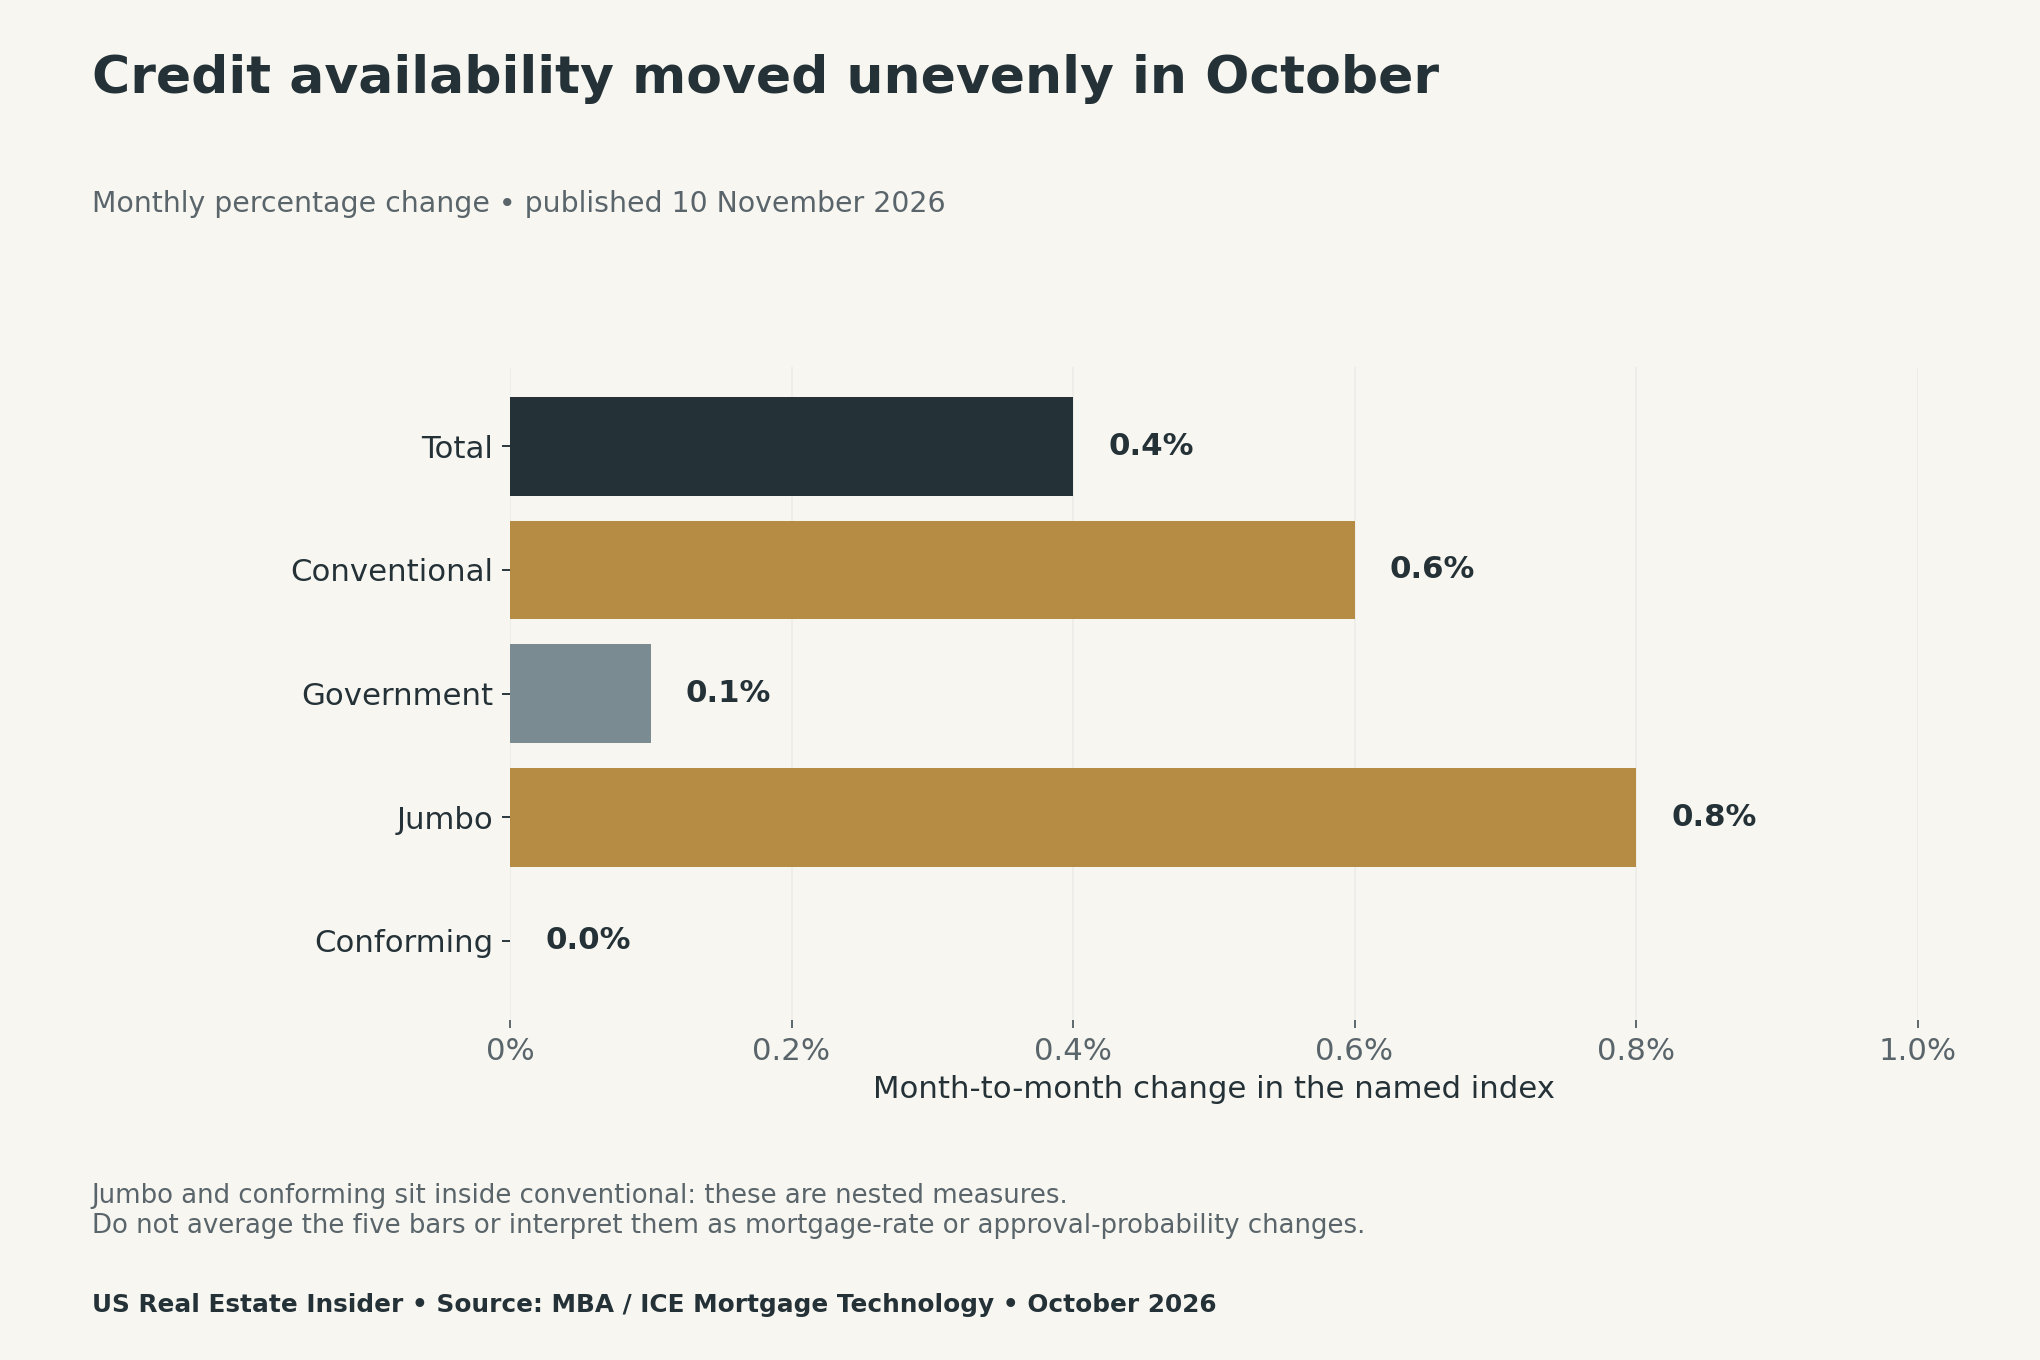
The Mortgage Bankers Association reported a 0.4% monthly rise to 107.5. Conventional availability rose 0.6%, government availability 0.1% and jumbo availability 0.8%; conforming was unchanged. Those different movements make a blanket “mortgages are easier for everyone” conclusion too broad.
What the mortgage credit availability release measures
MBA’s 10 November release covers October, rather than an individual application. Its MCAI combines eligibility and underwriting criteria from more than 95 lenders and investors using ICE Mortgage Technology data and a proprietary formula. The headline benchmark is March 2012 = 100.
MBA connects some expansion to additional adjustable-rate offerings for lower-loan-to-value borrowers, including certain cash-out products. This is a description of credit supply. It is not a reduction in every borrower’s mortgage rate, a count of approvals or a personal approval probability.
Keep the index level separate from the monthly change
The headline number 107.5 is an index level. Meanwhile, 0.4% describes MBA’s reported monthly change. Neither number is the percentage of people who qualify. MBA’s methodology FAQ explains the benchmark and why the index does not count available loans or dollars.
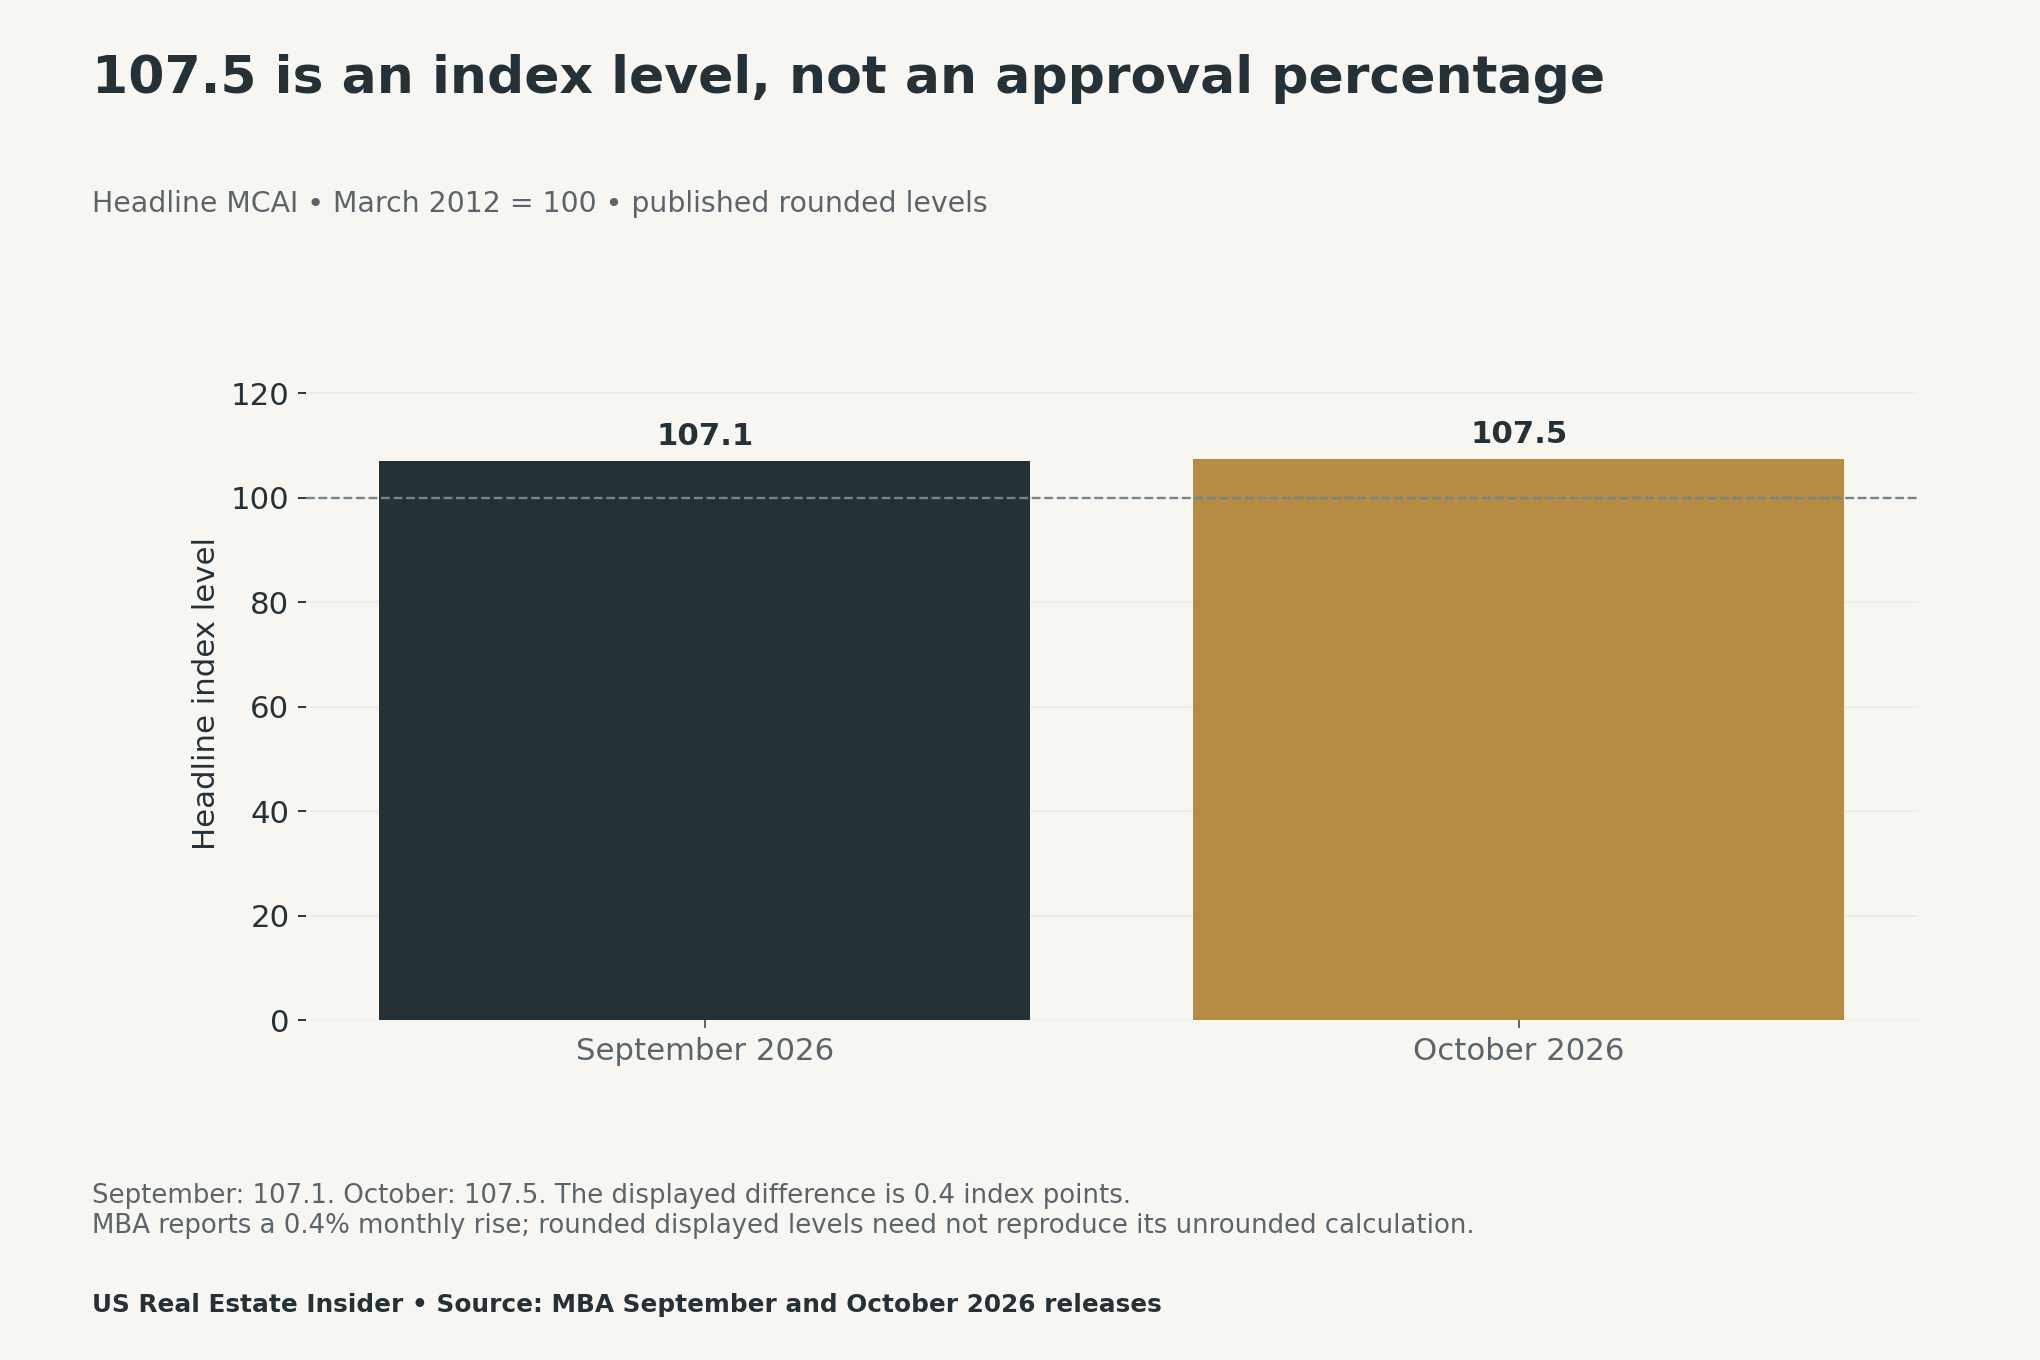
For example, subtracting the two rounded levels gives 0.4 points. That arithmetic is not a 0.4-percentage-point increase in approval rates. Consequently, the download keeps an explicit unit for each measure rather than placing all the numbers in one unlabeled column.
Do not average nested components
Conventional and government describe broad segments. Jumbo and conforming are components inside conventional. Therefore, a simple mean across all the displayed percentage changes would count overlapping information and ignore the publisher’s aggregation method.
We retain the source’s hierarchy in the data file. This small design choice helps a reader reuse the chart without turning it into an invented overall measure. The correct headline change comes from MBA, rather than our own average of segment labels.
Match the news to a fictional borrower situation
Our relevance matrix uses four invented situations, not four sampled borrowers. A first-time conforming buyer, a low-LTV jumbo inquirer, a government-backed buyer and a cash-out inquirer ask different questions. We assign no approval score, credit cutoff or probability to any of them.
| Fictional situation | Published context | Evidence still needed |
|---|---|---|
| First-time conforming purchase | Conforming unchanged | Ask whether a specific purchase program changed |
| Low-LTV jumbo inquiry | Jumbo +0.8%; some additional ARM offerings | Confirm loan purpose, LTV evidence and rate structure |
| Government-backed purchase | Government +0.1% | Ask about the exact program and current terms |
| Cash-out inquiry | Some lower-LTV ARM offerings mentioned | Verify permitted purpose, costs and equity requirements |
For the conforming example, an unchanged segment does not prove that every lender kept every program identical. However, it gives no basis for claiming broad easing from this release. The borrower should ask for a named current option and the conditions that actually changed.
For the jumbo example, the larger segment movement provides a reason to investigate, rather than a reason to assume suitability. A lower-LTV description also does not supply a numerical cutoff. Ask the lender what evidence and terms apply to the specific product today.
Separate product availability, borrower fit and underwriting
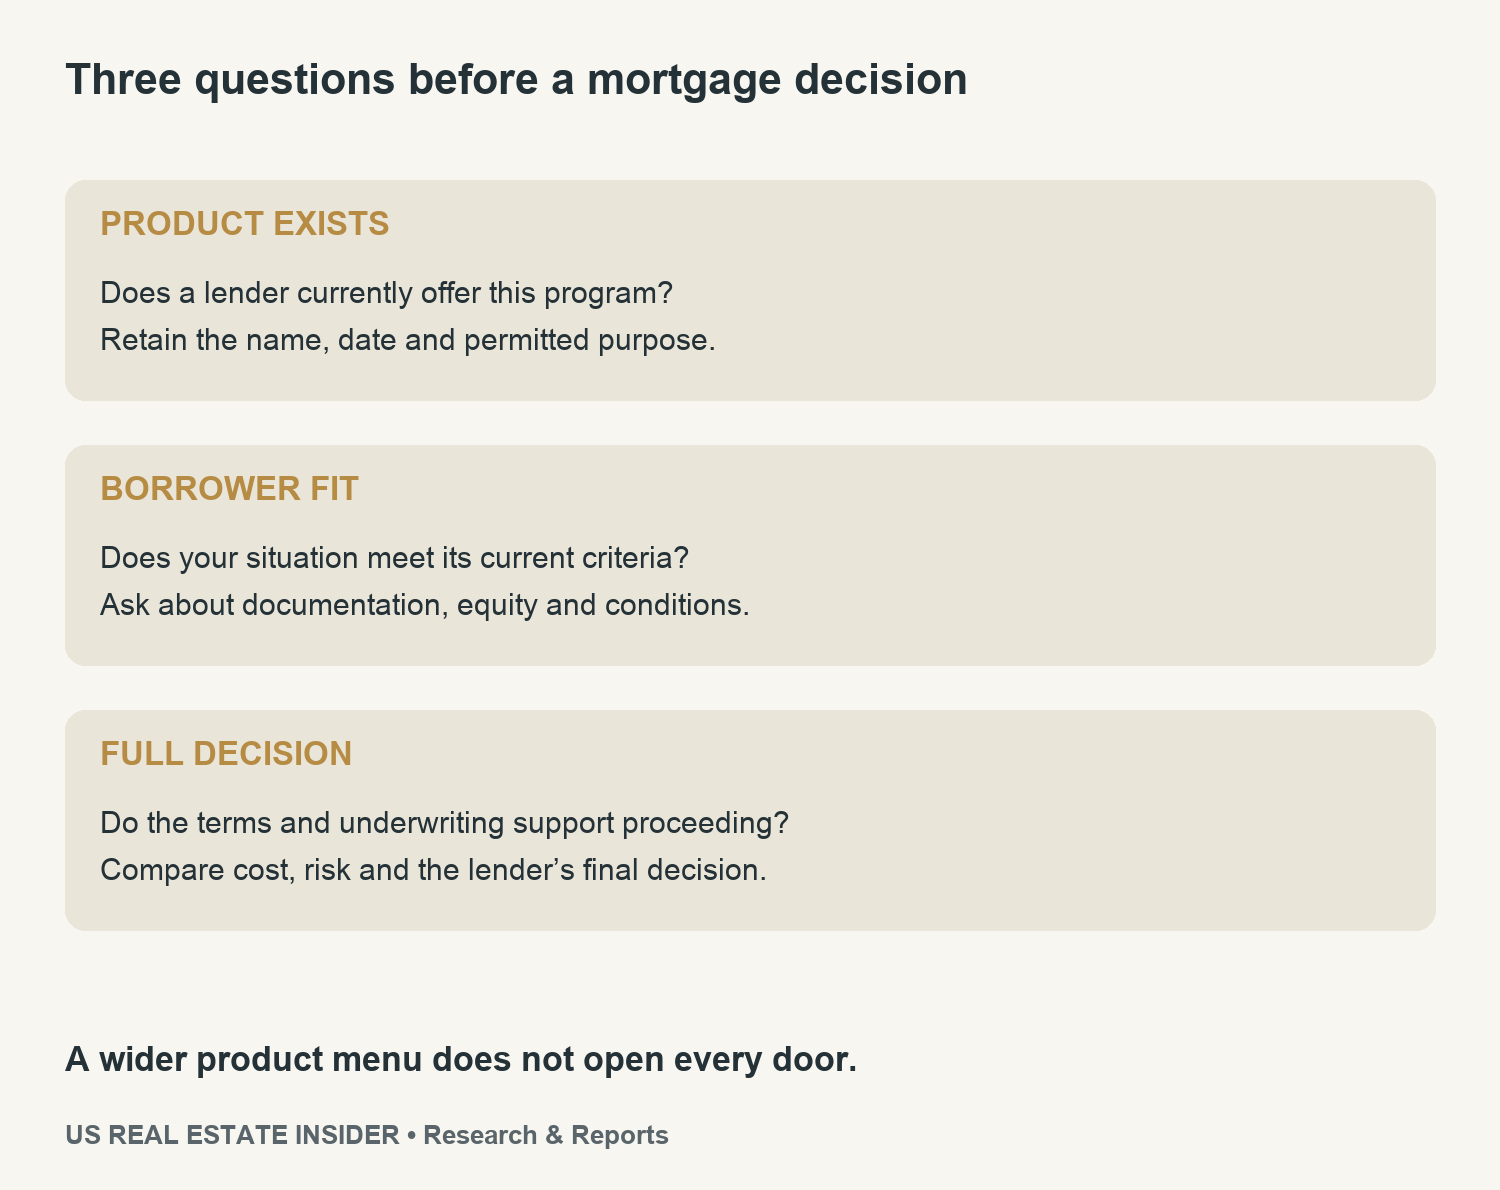
First, identify the program, lender, loan purpose and date. Next, ask about the actual documentation, equity requirements and conditions. Finally, compare the complete terms and the lender’s decision. A preliminary conversation or marketing headline cannot replace that review.
This sequence is useful even when the news does not lead to a new application. For instance, a borrower may discover that an added option serves a different purpose, requires different evidence or creates payment uncertainty they do not want. The worksheet makes that mismatch visible without predicting a decision.
Compare complete terms when a relevant option exists
The CFPB’s Loan Estimate comparison guide offers a practical framework for reviewing loan terms and costs. Use comparable assumptions and quote dates. Record what the monthly payment includes, the cash needed to close and whether the rate is locked.
For an adjustable-rate option, also inspect the adjustment terms. The CFPB explains rate caps, including limits on changes at different stages. A lower initial payment alone does not describe the full payment path or establish that the product fits your plans.
In addition, separate a new product from an affordable purchase. Taxes, insurance, association costs, repairs and other obligations can matter to the household budget. Our worksheet collects those questions; it does not quote a current rate, calculate an approval threshold or choose a mortgage for the reader.
Use a dated lender-question worksheet
The blank comparison sheet records the lender, program, quote date, purpose and documentation. It also asks for rate structure, adjustment information, fees, payment scope, cash to close and unresolved questions. Leave a field unknown until you have evidence rather than substituting a national statistic.
Keep private financial documents outside a public worksheet. A reader can maintain their own records securely and share only what an authorised professional needs. The downloadable examples contain no real applicants, lender quotations or sensitive account details.
Download the source-linked comparison tools
- October source measures and nested-segment labels (CSV)
- September and October published headline levels (CSV)
- Four fictional product-relevance examples (CSV)
- Blank lender-option comparison worksheet (CSV)
For the separate cash-reserve question, see our VA cash-to-close analysis. Our condo-cost comparison shows why an asking-price discount does not settle the household-cost question.
Methodology and limitations
We checked the first-party indexed MBA release text on 15 November 2026 and retained the release URLs, reported values, units and hierarchy. Direct MBA page access returned an access restriction during research; we did not bypass it or claim access to the proprietary underlying loan-level data.
The two charts reproduce selected published values and explicitly labelled arithmetic. The relevance matrix is an editorial teaching tool. No lender supplied an individual quote, and no application or underwriting test took place. Recheck a lender’s current criteria and obtain appropriate professional guidance for an individual financing decision.


